New VOC Regulations in the EU and US: What It Means for Your Cleaning Chemical Portfolio
Summary
Rules on volatile organic compounds (VOCs) in industrial cleaning solvents are tightening across the EU and US. Updated emission limits, stricter permitting and wider product category coverage take effect between 2024 and 2028. This article covers the regulations, the chemistry behind compliant alternatives, and what a delayed transition costs a business. Organizations that start portfolio transitions now can validate alternative chemistries under controlled conditions, while those that wait risk rushed substitutions, quality disruptions and premium compliance costs. It closes with a suggested timeline and checklist for planning a structured transition of a cleaning portfolio.
Table of Contents
I. The Regulatory Pressure on Industrial Cleaning Solvents
II. Current and Upcoming VOC Limits Across Major Markets
III. The Chemistry of Compliance: Solvent Families Under Pressure
IV. Aqueous and Semi-Aqueous Alternatives: Performance Trade-Offs
V. Business Impact of Delayed Portfolio Transitions
VI. Building a Portfolio Transition Strategy
VII. Key Takeaway
VIII. References
I. The Regulatory Pressure on Industrial Cleaning Solvents
The global industrial cleaning solvents market was valued at USD 51.7 billion in 2025 and is projected to reach USD 73.8 billion by 2033, a compound annual growth rate of 4.5 percent from 2026 to 2033 (Grand View Research, 2026). Regulation, more than demand, is increasingly shaping that growth. Governments across the EU, US and Canada are tightening VOC emission standards for industrial operations, and that is forcing a structural shift in how cleaning chemicals are formulated, selected and applied.
For technical managers who run cleaning chemical portfolios, the question is no longer whether they will need to move to lower-VOC alternatives. It is whether the move will be planned and validated, or reactive and disruptive. The regulatory timelines are concrete. Compliant chemistry also needs qualification testing, and that testing cannot be compressed into the final months before a deadline.
The Scale of the Shift
The growth figures hide a paradox. Overall demand is rising, yet the same report describes a gradual shift toward environmentally compliant, low-VOC formulations as regulatory requirements become more stringent (Grand View Research, 2026).
Industrial cleaning solvents can be a significant source of VOC emissions in manufacturing. Hydrocarbon solvents alone accounted for 35.5 percent of the industrial cleaning solvents market by revenue in 2025 (Grand View Research, 2026). Mineral spirits, naphtha, toluene and xylene face direct regulatory pressure under both EU and US frameworks. Moving away from these established chemistries changes more than the cleaning agent: it touches process parameters, equipment compatibility, waste handling and quality control protocols.
When several jurisdictions tighten on overlapping timelines, the effect compounds for organizations with international operations. A facility that supplies parts to both European and North American customers must now track separate VOC limits, exemption lists and reporting requirements for each market. In practice, the compliance target for a multinational operation becomes the most restrictive standard across all the jurisdictions that apply to it, and that increasingly means California-level or EU BAT-level restrictions.
II. Current and Upcoming VOC Limits Across Major Markets
VOC rules for industrial cleaning differ significantly by jurisdiction, but they move in one direction: limits are getting tighter, coverage is expanding, and enforcement is becoming more rigorous. Organizations that operate internationally or export to regulated regions need to know the specific requirements in each market.
EU: Industrial Emissions Directive and Solvents Emissions Directive
In the EU, the main instrument for VOC emissions from industrial operations is the Industrial Emissions Directive (IED, Directive 2010/75/EU). It replaced the earlier Solvents Emissions Directive (1999/13/EC), which was repealed with effect from 7 January 2014 (legislation.gov.uk, 2014). The IED sets emission limit values for VOCs in waste gases and maximum levels for fugitive emissions across solvent-using activities, surface cleaning included (European Chlorinated Solvents Association, 2024).
The revised directive, known informally as IED 2.0 (Directive (EU) 2024/1785), entered into force on 4 August 2024 (European Commission, 2024). EU Member States had until 1 July 2026 to transpose it into national law (European Parliament, 2024). The BAT reference documents (BREFs) are still being reviewed, and the first draft of the revised BREF for Surface Treatment of Metals and Plastics was published in February 2025 (European IPPC Bureau, 2025). For surface cleaning, the directive sets tight emission limits that are driving the use of closed cleaning machines (European Chlorinated Solvents Association, 2024).
For field operations this matters. Facilities now running under existing BAT conclusions may face revised, stricter requirements as updated BREFs are published. The first implementation phase of IED 2.0, which runs to 2030, includes developing a new regulatory environment and identifying BAT requirements for newly covered activities (European Commission, 2024). Organizations that assume current BAT conclusions will stay static risk being caught off guard: within four years of the publication of new BAT conclusions for an installation's main activity, the competent authority must ensure the installation complies with the updated permit conditions (European Union, 2010).
US: EPA Control Techniques Guidelines and State Implementation
In the United States, the EPA addresses VOC emissions from industrial cleaning solvents through a Control Techniques Guideline (CTG). A CTG is guidance and not legally binding on its own (EPA, 2006). It serves as the basis for state-level Reasonably Available Control Technology (RACT) requirements. States with certain ozone non-attainment areas must include RACT for VOC sources covered by a CTG in their state implementation plans (EPA, 2006), and many states have adopted standards based on the EPA CTGs or stricter than them.
California's consumer products regulation limits nonaerosol general purpose cleaners and general purpose degreasers to 0.5 percent VOC by weight, a limit in effect since 31 December 2012 (CARB, 17 CCR 94509). South Coast Air Quality Management District (SCAQMD) Rule 1171, which governs solvent cleaning operations, sets a VOC content limit of 25 grams per liter for general product cleaning and surface preparation, with higher limits for certain uses (SCAQMD, 2025). Amendments to Rule 1171 adopted on 6 June 2025 add a provision on carcinogenic materials and exempt compounds, so compliance now has a toxicity dimension as well as a VOC content limit.
Other states have adopted their own solvent cleaning rules. The patchwork adds complexity for organizations operating in several states: a company that wants one formulation for the whole country ends up treating the most restrictive standard that applies as its de facto national requirement.
Canada: VOC Concentration Limits for Certain Products
Canada's Volatile Organic Compound Concentration Limits for Certain Products Regulations, published in 2022, set VOC concentration limits for approximately 130 product categories and subcategories (Environment and Climate Change Canada, 2022). The maximum concentration limits came into effect on January 1, 2024, and the disinfectants category received one additional year to comply (Environment and Climate Change Canada, 2022). The regulations apply to Canadian manufacturers and importers of regulated products. Any analysis to determine VOC concentration under the regulations must be done by an accredited laboratory.
The Canadian regulation also includes a VOC Compliance Unit Trading System. A company can balance emissions from products that exceed the concentration limits with compliance units earned from products reformulated below the required limits. That turns compliance into a portfolio-level strategy: the system encourages reformulation across the full product range instead of treating each product in isolation.
Figure 1. VOC Regulatory Limit Comparison by Region and Application
Region | Regulatory Framework | Industrial Cleaning VOC Limit | Effective Timeline |
|---|---|---|---|
EU | Industrial Emissions Directive (IED 2.0) | BAT-AEL (waste gas), fugitive limits by activity | IED 2.0 entered force August 2024, national transposition by July 2026 |
US Federal | EPA CTG for Industrial Cleaning Solvents | Recommended RACT (guidance, not binding) | CTG published 2006, state implementation varies |
California | CARB Consumer Products | 0.5% VOC by weight (nonaerosol general purpose cleaners and degreasers) | Since 31 December 2012 |
California (SCAQMD) | Rule 1171 Solvent Cleaning Operations | 25 g/L VOC for general product cleaning and surface preparation | Amended June 2025; pCBtF and t-BAc limits from January 2026 |
Canada | VOC Concentration Limits Regulation | Category-specific limits for about 130 product categories | January 2024 (disinfectants one year later) |
The table shows how fragmented the rules are. Organizations with operations or customers in more than one region must plan for the most stringent applicable standard, and in practice that increasingly means California-level restrictions or EU BAT-AEL values.
III. The Chemistry of Compliance: Solvent Families Under Pressure
Regulatory tightening does not hit every cleaning chemistry equally. To see which solvent families are most affected, and why, you have to look at how molecular structure, vapor pressure and VOC classification relate. That chemistry decides which products in a cleaning portfolio face the most urgent pressure to transition.
High-VOC Solvent Families at Risk
Traditional industrial cleaning solvents can be grouped by VOC risk level according to their vapor pressure and photochemical reactivity. Chlorinated solvents such as trichloroethylene (TCE) and perchloroethylene (PCE) are restricted as VOCs and also under toxicity regulations. In December 2024 the EPA issued a final rule regulating PCE under the Toxic Substances Control Act. Its use in dry cleaning is phased out in stages beginning June 16, 2025, and all such uses are prohibited after December 19, 2034 (EPA, 2024). Aromatic hydrocarbons such as toluene and xylene are volatile and photochemically reactive, and both EU and US frameworks regulate them as VOCs.
Aliphatic hydrocarbons such as mineral spirits and naphtha are widely used in degreasing and parts washing. Some low-aromatics grades have been developed, but conventional formulations can exceed tight VOC content limits such as the 25 grams per liter in Rule 1171.
Oxygenated solvents, including ketones like methyl ethyl ketone (MEK) and acetone, sit in a more nuanced position. Acetone is on the US EPA list of compounds excluded from the VOC definition for negligible photochemical reactivity (US EPA, 40 CFR 51.100). The EU, however, counts acetone as a VOC, because its definition covers any organic compound with a vapour pressure of 0.01 kPa or more at 293.15 K (European Union, 2010).
VOC Exempt Solvents and Their Limitations
VOC exemption makes solvent selection more complicated still. The EPA keeps a list of compounds exempt from VOC classification because they contribute negligibly to tropospheric ozone formation. Acetone, parachlorobenzotrifluoride (pCBtF) and tertiary butyl acetate (t-BAc) are on that list (US EPA, 40 CFR 51.100), and they have been popular exempt solvents for cleaning. Recent developments, however, have challenged the assumption that exempt status gives long-term regulatory stability.
SCAQMD's June 2025 amendment to Rule 1171, under its provision on carcinogenic materials and exempt compounds, prohibits solvent cleaning with materials containing more than 0.01 percent by weight of pCBtF or t-BAc. It covers materials manufactured after January 1, 2026, with sell-through allowed until July 1, 2027 and use until July 1, 2028 (SCAQMD, 2025). The prohibition shows that VOC exemption does not shield a solvent from restrictions under other regulatory frameworks, particularly those addressing human health hazards.
Field engineers in the district who reformulated around these exempt solvents now face a second transition. Their situation makes the case for moving toward fundamentally lower-risk chemistries rather than exploiting regulatory exemptions.
The Alternatives Landscape
Replacement chemistries fall into three broad categories: aqueous cleaners, semi-aqueous cleaners and modified solvent systems. Each performs differently, and the right choice depends on the cleaning application, the substrate material, the contaminant type and the process constraints.
Aqueous cleaners use water as the primary carrier, with surfactants, builders and pH modifiers providing the cleaning action. They produce near-zero VOC emissions during application and are generally biodegradable. The trade-offs are longer drying times, a possible need for heated wash and rinse stages, and a corrosion risk on ferrous substrates unless they are properly formulated with corrosion inhibitors.
Semi-aqueous systems pair a solvent phase with a water rinse phase. On heavy hydrocarbon contamination they have better solvency than pure aqueous systems, and their VOC emissions are still significantly lower than those of traditional solvents. Bio-based glycol ethers and esters are the leading type of green solvent for industrial cleaning, projected at a 30 percent market share (Future Market Insights, 2026).
IV. Aqueous and Semi-Aqueous Alternatives: Performance Trade-Offs
Moving from solvent-based to aqueous or semi-aqueous cleaning is not a simple product substitution. The change shifts several process parameters at once, and the new performance envelope differs in ways that call for systematic evaluation, not assumption.
Critical Performance Parameters
Cleaning efficacy varies significantly with the contaminant. On light oils and water-soluble residues, aqueous cleaners can match or exceed solvent performance. Heavy greases, waxes and cured residues typically require semi-aqueous or modified solvent systems.
On flash point and fire safety, aqueous systems have the advantage, because they greatly reduce the risk of a flammable atmosphere. Drying time is often the most significant process impact. Water has a higher heat of vaporization, so parts need heated air drying, vacuum drying or extended ambient drying periods.
Material compatibility has to be evaluated for each substrate. Alkaline aqueous cleaners can etch aluminum and zinc alloys if pH is not carefully controlled. Some elastomers and plastics that are compatible with hydrocarbon solvents may swell or degrade in aqueous surfactant solutions.
Waste treatment changes fundamentally. Solvent-based waste is typically handled through distillation and reclamation or through hazardous waste disposal. Aqueous waste needs oil-water separation, pH adjustment and wastewater treatment, which may require new equipment or process modifications.
Process Redesign Considerations
Switching from solvent to aqueous cleaning often takes more than a chemistry change. The process has to be redesigned around a different cleaning mechanism, different rinsing requirements and different drying infrastructure. Solvent cleaning works mainly by dissolution: the solvent molecules surround the contaminant and dissolve it. Aqueous cleaning combines chemical action (surfactant-mediated emulsification and saponification), mechanical action (spray impingement, agitation or ultrasonics) and thermal energy (heated wash stages). Because of that mechanism, wash temperature, solution concentration, spray pressure and contact time become critical control parameters, and each has to be set through systematic trials.
Rinse water quality is something solvent-based operations rarely have to consider. Aqueous cleaning typically needs one or two rinse stages with controlled water quality so that residues do not form on the cleaned substrate. Precision cleaning may need deionized water rinses, which adds water treatment infrastructure to the transition cost. These process differences are why qualifying an aqueous alternative takes systematic evaluation under production conditions rather than simple bench-top trials.
Figure 2. Cleaning Technology Comparison Matrix
Parameter | Conventional Solvents | Aqueous Cleaners | Semi-Aqueous Systems | Modified Solvents (Low-VOC) |
|---|---|---|---|---|
VOC Emissions | High | Near zero | Low | Moderate |
Heavy Grease Removal | Excellent | Fair to Good | Good to Excellent | Good to Excellent |
Drying Time | Fast (seconds to minutes) | Slow (requires heating or vacuum) | Moderate | Fast to Moderate |
Substrate Compatibility | Broad (metals, plastics) | Requires pH control for reactive metals | Good with formulation tuning | Broad |
Fire/Safety Risk | High (low flash point) | Minimal | Low | Varies by formulation |
Waste Handling | Hazardous waste, distillation | Wastewater treatment | Combined waste stream | Similar to conventional |
Relative Cost per Liter | Low to Moderate | Low | Moderate to High | Moderate to High |
Qualification Effort | Established | High (process redesign) | Moderate | Low to Moderate |
Figure 3. Cleaning Technology Performance Profile Comparison (illustrative scores)
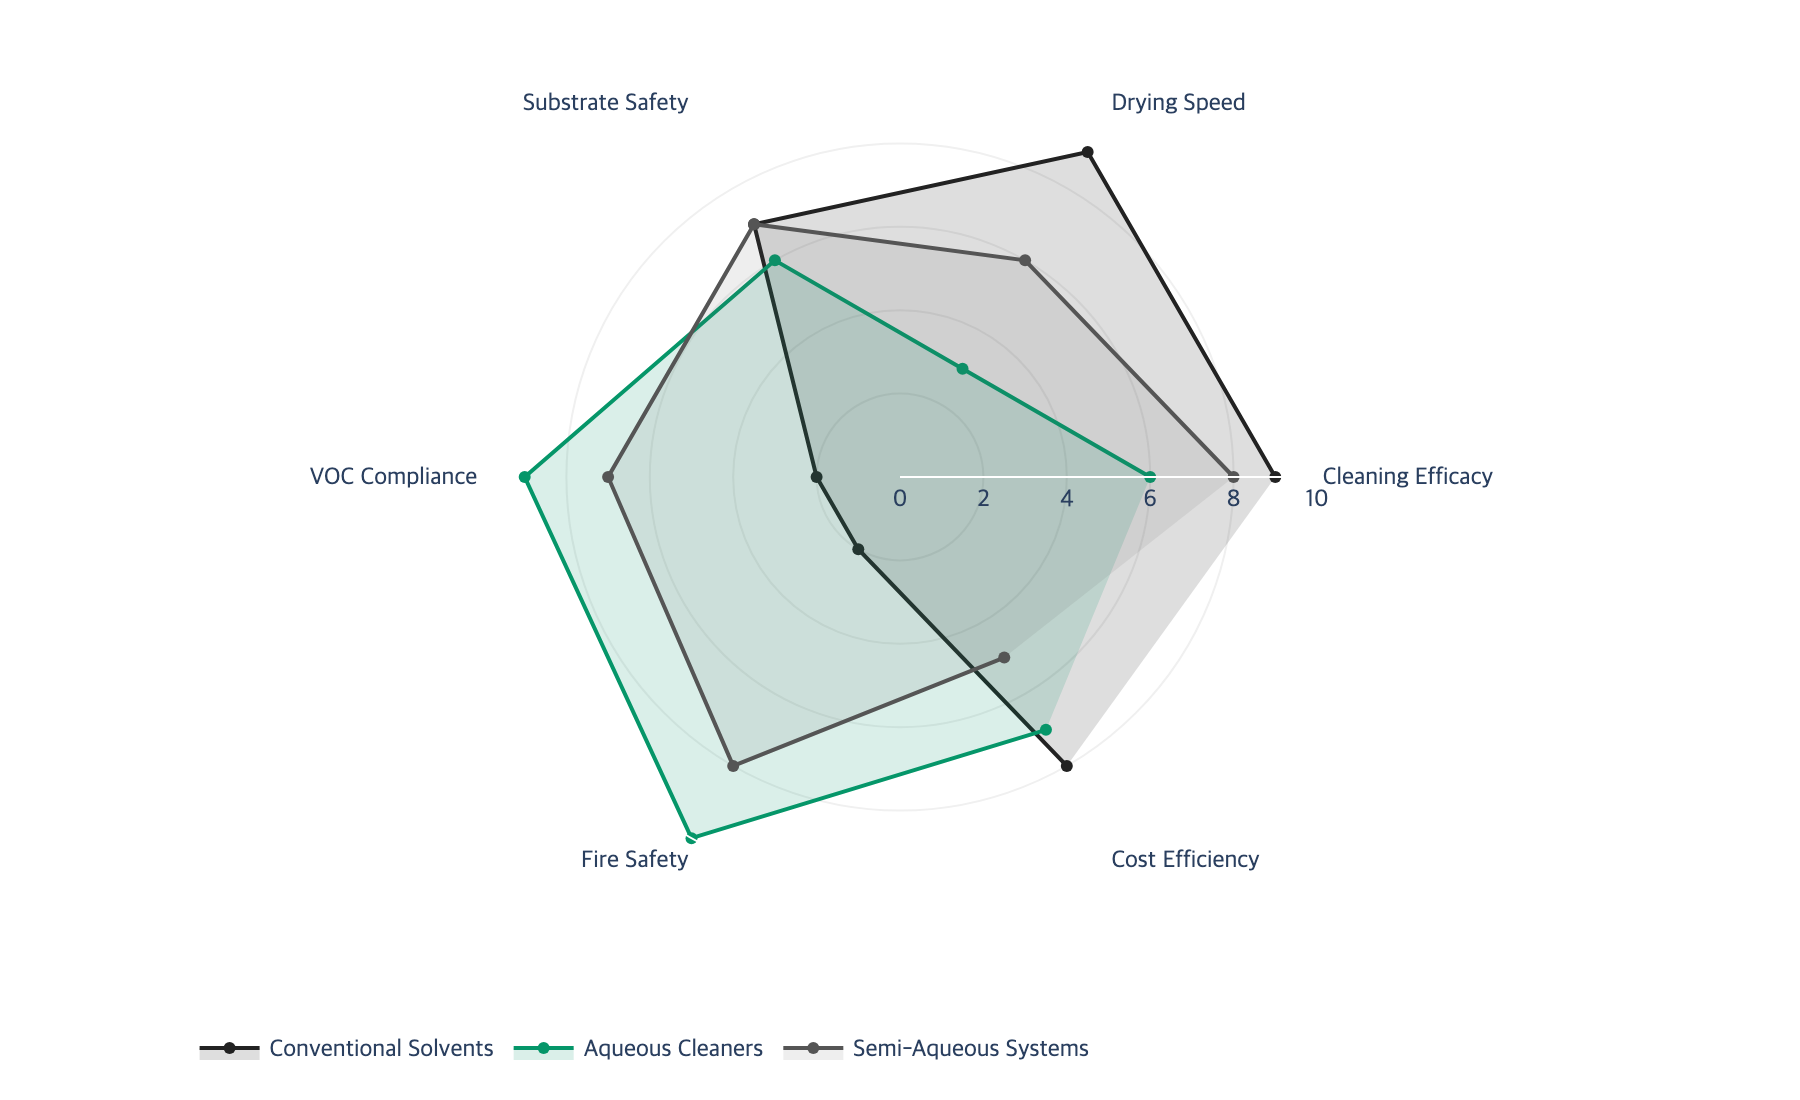
The radar chart gives an illustrative, qualitative view of the trade-offs across six performance dimensions; the scores are not measured values. Conventional solvents lead on cleaning efficacy and drying speed but score poorly on VOC compliance and fire safety. Aqueous cleaners reverse that pattern: they excel in compliance and safety but need process adjustments for drying and for removing heavy contamination. Semi-aqueous systems sit in the middle, with balanced performance that may suit applications where moderate trade-offs are acceptable.
No single alternative category is universally superior. The best choice depends on the application's requirements, and many organizations will need a mixed portfolio rather than one replacement technology. Watch the qualification effort entries closely when planning the transition, because they directly affect the timeline and cost of switching.
V. Business Impact of Delayed Portfolio Transitions
The financial cost of a delayed portfolio transition goes well beyond non-compliance fines. Organizations that start late can face a cascade of added costs, and the total can end up higher than the cost of a planned, early transition.
The Cost Multiplication Effect
Qualification testing under time pressure can require accelerated test protocols, overtime labor and sometimes parallel testing of several candidates instead of sequential evaluation of the most promising options. The EPA estimated that replacing high-VOC cleaning materials with low-VOC water-based materials in many cleaning operations would save about USD 1,460 per megagram of VOC reduced, counting only cleaning material and waste disposal costs (EPA, 2006). Rushed, the same switch can cost more, because of emergency equipment procurement, expedited supplier qualification and production disruptions during changeover.
Qualifying a change to a cleaning process typically takes consecutive successful runs under production conditions. Each run must produce documented evidence of cleaning performance, substrate integrity and process consistency. Compress those runs into weeks instead of months and the chance of hitting unresolved issues can rise. A failed run costs more than the length of one run: it can trigger root cause investigation, corrective action and a restart of the qualification sequence, potentially adding months to a timeline that was already compressed.
Operator Training and Institutional Knowledge
Operator training is another cost that depends on time. Aqueous and semi-aqueous processes need different handling procedures, quality checkpoints and troubleshooting approaches from solvent systems. Compressed training can lead to higher error rates during the transition, which show up as cleaning quality defects, substrate damage or process bottlenecks.
Training is harder still because the two kinds of system fail differently. Solvent cleaning failures are often visible and immediate: the parts are clean or they are not, and the solvent dissolves the contaminant or it does not. Aqueous cleaning failures can be subtle and delayed. Insufficient rinsing may leave surfactant residues that only show up in later coating or bonding operations. Incorrect concentration or temperature settings may clean some substrates acceptably while micro-etching others. Diagnosing failures like these takes a different mindset, and that mindset takes time to develop through hands-on experience.
Supply Chain Vulnerability
Late movers can run into supply constraints as demand for alternative chemistries rises ahead of regulatory deadlines. Specialty surfactants, bio-based solvents and qualified aqueous formulations have lead times that can stretch during periods of high demand. An organization that waits until the final year before a deadline may find its preferred alternatives on allocation, and then has to accept less-optimal substitutes or premium pricing.
Qualification makes the supply risk worse. If an organization qualifies Alternative A and then finds it unavailable at volume, switching to Alternative B requires a new round of qualification testing. The resulting chain of delays can push compliance past the regulatory deadline. Securing supply agreements for qualified alternatives well before the compliance date can provide both price stability and supply assurance.
VI. Building a Portfolio Transition Strategy
A structured transition strategy turns regulatory pressure into an operational advantage. It depends on starting early enough that each phase can be completed without compromising quality or disrupting production.
Portfolio Risk Assessment
Before the transition begins, organizations should run a portfolio-level risk assessment that maps every cleaning product in current use against the regulatory requirements of every jurisdiction they operate in. For each product, record the product name, manufacturer, VOC content by weight, annual consumption volume, application type, substrate cleaned, and the most restrictive VOC limit that applies to that application. Products whose VOC content exceeds the applicable limit should be flagged for priority transition. A suggested rule of thumb, not a regulatory requirement, is to also flag products within 20 percent of the limit, as a buffer in case limits are tightened further during the transition period.
Transition Planning Checklist
The framework below is a suggested plan for cleaning portfolio transitions, not a regulatory requirement or a measured industry benchmark. Each phase has its own deliverables and a suggested timing relative to the regulatory compliance date. Adjust the timings to each site's equipment, qualification and supply lead times.
Phase 1: Portfolio Audit (18-24 months before deadline). Inventory all cleaning solvents by product, application, volume and VOC content. Identify products that exceed current or anticipated regulatory thresholds. Map each product to its specific regulatory requirement in each jurisdiction. Prioritize transitions by the size of the VOC exceedance, consumption volume and application criticality.
Phase 2: Alternative Identification (15-18 months before deadline). For each at-risk product, identify two to three candidate alternatives. Classify the alternatives by technology type (aqueous, semi-aqueous, modified solvent). Assess equipment compatibility and identify any capital requirements. Request technical data sheets and safety data sheets from candidate suppliers, and verify their VOC content claims against the applicable regulatory definition, because the EU and US definitions of VOC differ.
Phase 3: Qualification Testing (9-15 months before deadline). Run laboratory-scale cleaning trials with candidate alternatives. Test on actual production substrates with representative contamination. Evaluate every critical parameter: cleaning efficacy, drying time, substrate compatibility and waste handling. Plan for consecutive successful qualification runs under production conditions to validate the selected alternative.
Phase 4: Process Integration (6-9 months before deadline). Run pilot-scale production trials with the selected alternatives. Train operators on the new procedures and quality checkpoints, and allow enough time for hands-on experience with the new failure modes and diagnostic approaches. Update standard operating procedures and quality control documentation. Set up waste handling procedures for the new chemistry, including any wastewater treatment requirements.
Phase 5: Full Deployment (3-6 months before deadline). Complete the full production changeover with parallel monitoring. Establish baseline performance metrics for the new cleaning program. Document compliance status for regulatory reporting. Secure supply agreements for the qualified alternative at production volumes, with backup supply sources identified.
Because each step informs the next, the phased approach lowers the risk of selecting an alternative that fails in production or needs unexpected equipment modifications. The suggested total of 18 to 24 months reflects that qualification testing, equipment procurement and operator training are hard to compress without increasing risk.
VII. Key Takeaway
VOC regulations for industrial cleaning are tightening across major markets: the EU's IED 2.0 entered into force in August 2024 (transposition by July 2026), Canada's VOC limits for about 130 product categories took effect in January 2024, and SCAQMD amended Rule 1171 in June 2025. Long-standing limits still apply as well, such as California's 0.5 percent VOC cap for nonaerosol general purpose cleaners.
VOC-exempt solvents are not a permanent safe harbor. SCAQMD's 2025 limits on t-BAc and pCBtF in solvent cleaning show that exempt status does not protect a solvent from health-based restrictions, so organizations should plan for fundamentally lower-risk chemistries.
No single alternative technology replaces every conventional solvent application. Portfolio transitions need an application-specific evaluation of aqueous, semi-aqueous and modified solvent options, with attention to the process redesign each requires, including rinse stages, drying infrastructure and water treatment.
A rushed transition can cost more in total than a planned one, driven by accelerated testing, emergency procurement, compressed training and production disruptions.
As a suggested plan, begin portfolio audits 18 to 24 months before regulatory deadlines, to allow time for qualification testing, operator training with parallel operation periods, and supply agreements.
Organizations that complete transitions early can gain operational stability, validated processes and potential cost savings from lower-VOC chemistry, while late movers risk premium costs and quality problems.
VIII. References
[1] Grand View Research, "Industrial Cleaning Solvents Market Size Report, 2026-2033", 2026. https://www.grandviewresearch.com/industry-analysis/industrial-cleaning-solvents-market-report
[2] The National Archives (legislation.gov.uk), "Council Directive 1999/13/EC on the limitation of emissions of volatile organic compounds (repealed)", 2014. https://www.legislation.gov.uk/eudr/1999/13/2010-12-01
[3] European Chlorinated Solvents Association, "Industrial Emission Directive (IED) and Chlorinated Solvents", 2024. https://www.chlorinated-solvents.eu/regulatory/voc-regulation-ied/
[4] European Commission, "Industrial and Livestock Rearing Emissions Directive (IED 2.0)", 2024. https://environment.ec.europa.eu/topics/industrial-emissions-and-safety/industrial-and-livestock-rearing-emissions-directive-ied-20_en
[5] European Parliament, "Legislative Train: Revision of Directive 2010/75/EU on industrial emissions (REFIT)", 2024. https://www.europarl.europa.eu/legislative-train/theme-a-european-green-deal/file-revision-of-the-industrial-emissions-directive-(refit))
[6] European IPPC Bureau, "BAT Reference Documents under the IED", 2025. https://bureau-industrial-transformation.jrc.ec.europa.eu/reference
[7] European Union, "Directive 2010/75/EU on industrial emissions, Article 21 (Reconsideration and updating of permit conditions) and Article 3 (Definitions)", 2010. https://www.legislation.gov.uk/eudr/2010/75/article/21 and https://www.legislation.gov.uk/eudr/2010/75/article/3
[8] US EPA, "Control Techniques Guidelines: Industrial Cleaning Solvents", 2006. https://www3.epa.gov/airquality/ctg_act/200609_voc_epa453_r-06-001_ind_cleaning_solvents.pdf
[9] California Air Resources Board, "Standards for Consumer Products, California Code of Regulations Title 17, Section 94509". https://www.law.cornell.edu/regulations/california/17-CCR-94509
[10] SCAQMD, "Rule 1171: Solvent Cleaning Operations (amended June 6, 2025)", 2025. https://www.aqmd.gov/docs/default-source/rule-book/reg-xi/rule-1171.pdf
[11] Environment and Climate Change Canada, "Volatile Organic Compound Concentration Limits for Certain Products Regulations", 2022. https://gazette.gc.ca/rp-pr/p2/2022/2022-01-05/html/sor-dors268-eng.html
[12] US EPA, "Fact Sheet: Final Risk Management Rule for Perchloroethylene (PCE) under TSCA", 2024. https://www.epa.gov/system/files/documents/2025-01/pce-fact-sheet_english.pdf
[13] US EPA, "40 CFR 51.100: Definitions (volatile organic compounds and excluded compounds)". https://www.law.cornell.edu/cfr/text/40/51.100
[14] Future Market Insights, "Green Solvents for Industrial Cleaning Market: Global Market Analysis Report, 2036", 2026. https://www.futuremarketinsights.com/reports/green-solvents-for-industrial-cleaning-market
Updated 2026-10-23: checked figures and sources; removed outdated product references

